

Financial influencer Taylor Price joins ‘Varney & Co.’ to break down how shifting your mindset can help Americans grow wealth and achieve the American Dream.
**Key Takeaways:**
1. **Significant Financial Drain:** Family caregivers face an average out-of-pocket expenditure of $11,508 annually, consuming nearly a third (31%) of their household income, a burden that disproportionately impacts lower-income families who can spend up to 76% of their income on care.
2. **Exacerbated by Complexity:** Costs surge for caregivers assisting individuals with dementia ($15,846 annually) or performing complex medical tasks, forcing many to deplete retirement savings or incur debt, raising concerns about long-term financial stability and asset depletion.
3. **Broad Economic Ramifications:** This financial strain creates a ripple effect across the economy, impacting workforce participation, consumer spending, demand for financial products, and placing additional pressure on an already stretched healthcare system, signaling potential fiscal drag and demographic challenges.
**The Unseen Economic Burden: How Caregiving Strains Household Finances and Markets**
The silent crisis of family caregiving is increasingly becoming a loud signal for market analysts and policymakers alike. A new study reveals that the personal sacrifices of caregivers translate into a significant economic drain, with profound implications for household wealth, labor markets, and various industry sectors. On average, family caregivers are shelling out more than $11,000 a year from their own pockets to care for loved ones, a staggering sum that consumes nearly a third of their household income. This isn’t just a personal hardship; it’s a growing economic headwind.
The recent study, released by AARP, paints a stark picture: caregivers spend an average of $11,508 annually out of pocket while tending to an adult relative or friend. This figure, representing an average of 31% of household income, highlights a critical erosion of disposable income for a substantial segment of the population. From a market perspective, this reduction in discretionary spending power can have a dampening effect on retail sales, consumer confidence, and broader economic growth. When nearly a third of a household’s income is diverted to essential caregiving costs, less is available for investments, home improvements, or non-essential goods and services, directly impacting corporate revenues and potentially equity valuations in consumer-facing sectors.
The financial burden, however, is not evenly distributed; it magnifies for lower-income households, creating a worrying trend of economic inequality. Caregivers with annual household incomes below $40,000 are forced to dedicate an average of 76% of their income to caregiving expenses. This almost-total consumption of income means these families are living on the brink, with virtually no buffer for emergencies, savings, or long-term financial planning. This demographic’s inability to save or invest perpetuates cycles of poverty and limits their access to wealth-building opportunities, posing systemic challenges for social mobility and economic inclusion. For financial institutions, this represents a segment increasingly reliant on credit, potentially increasing default risks or, conversely, an untapped market for targeted, affordable financial products if solutions emerge.
**ECONOMIST SAYS OBAMA ‘FUNDAMENTALLY BROKE’ US HEALTHCARE SYSTEM, REVEALS SIMPLE FIX FOR REPUBLICANS**
Family caregivers are shelling out more than $11,000 a year on average to care for loved ones, consuming nearly a third of their household income.(iStock)
A deep dive into the cost categories reveals where these significant outlays are occurring. Household and housing expenses constitute the largest share of out-of-pocket spending, averaging $4,797 a year. This category includes fundamental necessities such as food, rent, and mortgage payments, underscoring how caregiving impacts basic living costs. In a climate of persistent inflation, particularly in housing and food prices, these expenses exert even greater pressure. Real estate markets, already contending with affordability issues, are indirectly affected as caregivers might delay home purchases, struggle with existing mortgage payments, or be forced to downsize. The food retail sector, while seeing consistent demand, might observe shifts towards more budget-friendly options as household budgets tighten.
Medical expenses form another substantial component, averaging $3,313 annually. This includes a broad spectrum of costs: copayments, insurance premiums, prescription drugs, medical equipment, and direct payments to healthcare providers. These figures directly reflect the broader trend of rising healthcare costs in the U.S., which continue to outpace wage growth. For insurers, this indicates sustained claims pressure, while pharmaceutical companies and medical equipment providers see ongoing demand. However, the reliance on out-of-pocket spending highlights gaps in insurance coverage and the necessity for more comprehensive long-term care solutions, signaling potential for disruption in the health and long-term care insurance markets.
The financial burden climbs even higher when the care recipient’s condition is more complex. Those caring for someone with Alzheimer’s disease or another form of dementia spend an average of $15,846 annually, significantly more than the $10,221 spent by those caring for someone without dementia. This 50% increase in costs is a stark reminder of the escalating financial demands associated with cognitive decline, a growing concern given aging global demographics. Similarly, caregivers performing three or more medical or nursing tasks face average annual expenditures of $15,648, nearly double the $7,948 spent by those performing none. These statistics underscore the critical need for specialized support and potentially higher reimbursement rates for skilled home care services, which could spur growth in specific sub-sectors of the healthcare industry.
**TRUMP ANNOUNCES $275M NURSING-HOME NURSE INITIATIVE AT FLORIDA MIDTERM RALLY**
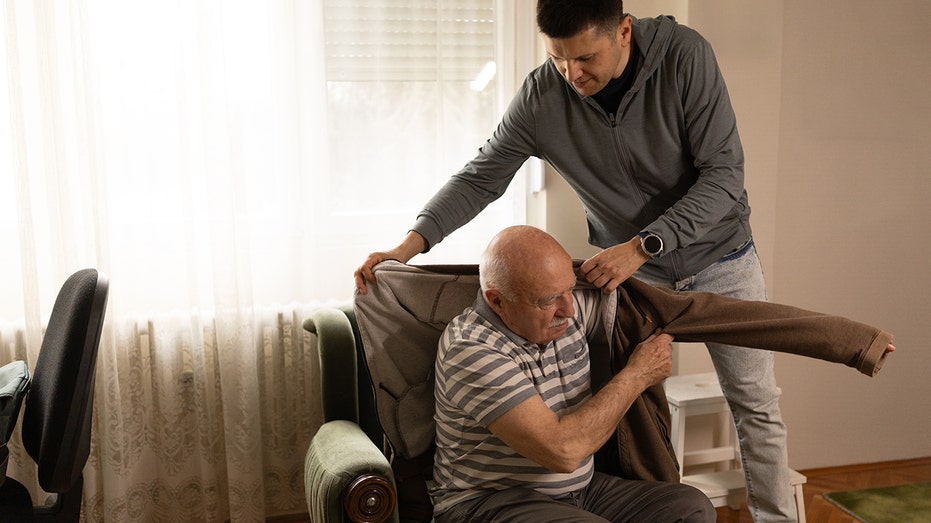
Household and housing expenses make up the largest share of out-of-pocket spending, averaging $4,797 a year.(iStock)
The financial strain inevitably spills over into caregivers’ professional lives and long-term savings. Nearly two-thirds of working caregivers surveyed reported at least one work-related impact tied to caregiving responsibilities. This includes missed work, reduced hours, career stagnation, or even leaving the workforce altogether. Working caregivers, on average, spend $12,606 annually on care, demonstrating the dual burden of maintaining employment while managing significant care costs. Those who take on additional jobs to cover expenses often find themselves in a vicious cycle, spending an average of $16,851 a year on caregiving, indicative of an unsustainable work-life balance that can lead to burnout and reduced productivity. This phenomenon has broader macroeconomic implications, potentially affecting labor force participation rates, corporate productivity, and ultimately, national GDP. Companies might face higher turnover rates and difficulty retaining experienced employees, prompting an increased focus on employee support programs and flexible work arrangements.
Critically, many caregivers are resorting to desperate measures to cover these mounting expenses. Some are turning to borrowing money or taking out loans, with those relying on credit spending an average of $16,580 annually on caregiving. Even more concerning, a significant portion is dipping into their retirement savings, with expenditures averaging $17,907 for those who tap into these crucial long-term assets. This depletion of retirement funds poses a severe threat to the financial security of caregivers in their later years, exacerbating the broader retirement crisis and placing future strain on social safety nets. For the financial services industry, this highlights both a challenge in client retention and an opportunity for specialized financial planning services that integrate long-term care considerations. The demand for accessible credit and loan products that specifically address caregiving needs may also rise, requiring careful risk assessment by lenders.
**MICROSOFT SAYS ITS AI TOOL OUTPERFORMS GENERALIST DOCTORS IN COMPLEX DIAGNOSES**
The financial strain can also spill into caregivers’ jobs and savings.(iStock)
**Market Impact:**
The escalating financial burden on family caregivers is not merely a social issue but a significant economic force shaping various market sectors. The erosion of household disposable income directly impacts consumer discretionary spending, potentially slowing growth in retail, leisure, and hospitality industries. The increased reliance on borrowing and depletion of retirement savings signals a growing demand for credit products and specialized financial planning services, while also raising long-term concerns about retirement security and future government expenditures on social programs. In the healthcare sector, the data underscores persistent cost pressures and the need for innovation in long-term care insurance, home health services, and elder care technology. Furthermore, the impact on workforce participation and productivity could create labor market inefficiencies, prompting employers to invest more in caregiver support programs. Overall, the trend points towards a fiscal drag on the economy, demanding both policy interventions and private sector solutions to mitigate the financial strain and unlock the economic potential of this crucial demographic.
**CLICK HERE TO GET FOX BUSINESS ON THE GO**