
Stay informed with free updates
Simply sign up to the War in Ukraine myFT Digest — delivered directly to your inbox.
Key Takeaways:
- Geopolitical Risk Premium Rises:The immediate aftermath of renewed missile strikes and stalled diplomatic efforts points to an elevated geopolitical risk premium across global markets, potentially driving a flight to safety and increased volatility.
- Energy Market Volatility Ahead:Attacks on Ukrainian energy infrastructure, coupled with the impending winter, signal persistent upside risks for European natural gas and global crude oil prices, impacting inflation and energy security narratives.
- Defense Sector Tailwind:The protracted conflict and demonstrated need for sophisticated air defense systems continue to underscore a robust outlook for defense contractors, buoyed by increased government spending and rearmament initiatives.
Kyiv Endures Barrage as Diplomatic Hopes Fade, Sparking Market Jitters
In a stark reminder of the persistent geopolitical risk emanating from Eastern Europe, Russia unleashed a devastating barrage of missiles on Kyiv overnight, just hours after US President Donald Trump’s special envoy, Steve Witkoff, concluded talks in St. Petersburg that failed to yield a meaningful breakthrough for peace in Ukraine. The renewed aggression, targeting critical infrastructure and civilian areas, immediately sent shockwaves through market sentiment, amplifying concerns over prolonged conflict and its broader economic ramifications.
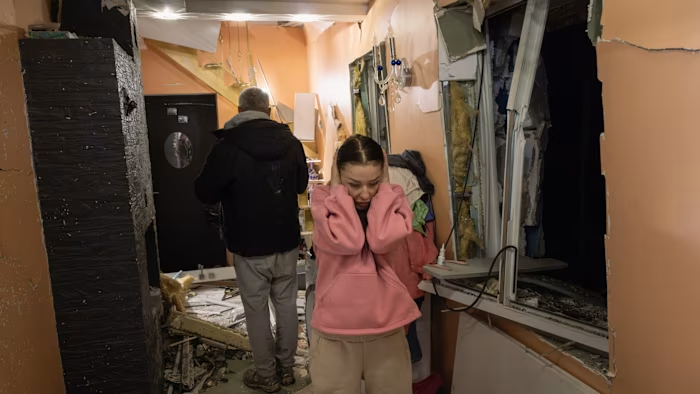
Over 20 ballistic missiles rained down on the Ukrainian capital, triggering air raid sirens and forcing residents into shelters late Wednesday and through the night. The attacks resulted in at least one fatality and 22 injuries, according to Ukraine’s emergency services. Kyiv Mayor Vitali Klitschko confirmed damage to an ambulance station, metro infrastructure near the vital South Bridge, and commercial properties, with local reports indicating the destruction of a shopping centre across six districts. Such widespread targeting underscores a strategic intent that extends beyond military objectives, aiming to destabilize daily life and cripple urban functionality, factors which directly feed into heightened country risk assessments by international investors.
The timing of these strikes is particularly salient, following a renewed but ultimately fruitless US diplomatic push. Envoy Witkoff met with Ukrainian President Volodymyr Zelenskyy and several European leaders in Oslo earlier in the week before heading to St. Petersburg for direct talks with Russian President Vladimir Putin. Despite Witkoff’s controversial public characterization of Putin as a “humanitarian,” the overnight events provided a brutal rebuttal, with Ukraine’s foreign minister Andriy Sybiha sarcastically noting on X, “Overnight, Kyiv residents heard what Russian ‘humanism’ truly sounds like.” This public exchange highlights the chasm between diplomatic rhetoric and the harsh realities on the ground, leaving investors to grapple with the implications of an unyielding conflict that continues to defy conventional diplomatic solutions, thus prolonging uncertainty in global markets.
The failure of these high-level discussions to secure any tangible progress, particularly on Ukraine’s urgent plea for an “energy ceasefire” ahead of the harsh winter months, has significant implications for global energy markets. Kyiv has consistently sought to halt Russia’s systematic targeting of its power plants and energy infrastructure, a strategy clearly designed to weaken Ukrainian resolve and economic resilience. Conversely, the Trump administration has previously pressured Ukraine to cease its own strikes on Russian refineries and oil terminals, illustrating the complex and often contradictory pressures at play in a conflict with global energy repercussions. This dynamic presents a challenging balancing act for commodity traders and energy policy makers alike, as any perceived escalation in either direction can quickly ripple through prices.
The continued targeting of energy assets in Ukraine, coupled with the looming winter heating season, introduces an acute risk premium into European natural gas and global crude oil futures. Analysts are closely watching inventories and supply routes, wary that any major disruption could send prices surging, reigniting inflationary pressures that central banks globally have been striving to tame. For European economies, still navigating the aftershocks of previous energy crises, prolonged instability in Ukraine’s energy grid poses a direct threat to industrial production and household budgets. Traders in London and Frankfurt are already pricing in higher volatility for energy-related derivatives, reflecting the heightened uncertainty surrounding winter energy supply and demand dynamics across the continent.
Furthermore, the conflict’s persistence reinforces the robust demand outlook for the global defense sector. The ongoing need for sophisticated air defense systems, exemplified by the interception of Russian missiles over Kyiv, underscores a sustained commitment to military expenditure among NATO allies and partners. Companies specializing in missile defense, surveillance technology, and advanced armaments are likely to see continued order inflows, bolstering their long-term revenue prospects. This dynamic creates a distinct pocket of resilience within equity markets, offering a defensive play for institutional investors seeking sectors insulated from broader economic downturns or geopolitical turmoil, with defense contractors becoming key beneficiaries of increased geopolitical instability.
While President Zelenskyy mentioned receiving “feedback” about a potential revival of trilateral talks involving Ukraine, Russia, and the US in early November – discussions that have been dormant since the onset of the war – the recent missile barrage casts a long shadow over any nascent hopes for de-escalation. The absence of a confirmed date and the immediate resumption of hostilities suggest that any diplomatic path remains fraught with challenges, implying that markets should anticipate continued volatility and a sustained geopolitical risk premium for the foreseeable future. This prolonged uncertainty hinders foreign direct investment into the region and postpones any significant reconstruction efforts, keeping Ukraine’s sovereign risk profile elevated.
The financial world’s reaction to these developments is typically characterized by a flight to safety. Investors tend to reallocate capital towards perceived safe-haven assets such as gold, the US dollar, and sovereign bonds (particularly U.S. Treasuries and German Bunds), driving down yields in the latter. Emerging markets, especially those geographically proximate to the conflict or heavily reliant on commodity exports, may experience increased capital outflows and currency depreciation as risk aversion intensifies. Equity markets, particularly those with significant exposure to European energy or industrial sectors, are likely to exhibit heightened sensitivity to further escalations or diplomatic impasses, with indices potentially pulling back on volume.
Market Impact:
The failure of recent peace talks coupled with Russia’s renewed missile assault on Kyiv will likely inject a fresh wave of caution into global financial markets. Commodity prices, specifically Brent crude and European natural gas futures, are expected to trade with an elevated geopolitical risk premium, potentially pressuring energy-sensitive equities and contributing to broader inflation concerns that may influence central bank policy. Equity markets, particularly in Europe, may experience increased volatility and a “risk-off” sentiment, leading to flows into safe-haven assets such as gold, the U.S. dollar, and government bonds, compressing yields. The Ukrainian Hryvnia (UAH) will face renewed downward pressure, while broader emerging market currencies may also weaken. Defense sector stocks, however, are likely to remain resilient or see further upside as sustained conflict translates into continued demand for military hardware and services, acting as a defensive hedge in volatile times.