
A Capitol One bank branch in Manhattan, New York, was targeted with anti-Israel messages by vandals who smashed multiple windows, according to video taken by Ken Lopez of FNTV.
Key Takeaways:
- Political Scrutiny vs. Financial Fundamentals:New York City Comptroller Mark Levine’s decision to halt Israel Bond purchases, reversing a campaign pledge, is drawing sharp criticism for prioritizing alleged political considerations over the bonds’ competitive yields and Israel’s strong financial track record, which includes an unblemished repayment history over 75 years.
- Competitive Yields & Sovereign Strength:Israel Bonds’ CEO highlights attractive current yields (up to 6.44% for 10-year bonds), robust Israeli economic indicators (low unemployment, modest inflation, strong growth forecasts), and stable investment-grade credit ratings from major agencies, presenting a compelling case for financial prudence.
- Implications for Public Fund Management:The controversy raises critical questions about the role of political influence in municipal investment decisions, the fiduciary responsibilities of public officials, and how market participants weigh geopolitical risks against established financial performance and creditworthiness in a high-interest-rate environment.
New York City’s financial relationship with Israel, a tradition spanning nearly five decades, has been disrupted as City Comptroller Mark Levine declined to reinstate investments in Israel Bonds. This move, a reported reversal of a prior campaign commitment, is sparking a heated debate about the intersection of financial prudence, political influence, and fiduciary duty within public fund management, particularly amidst a volatile global market landscape where bond yields have been hovering near multi-year highs.
Comptroller Levine is facing intense scrutiny over his decision, which Israel Bonds President and CEO Dani Naveh learned of through news reports. Naveh has directly challenged Levine’s financial rationale, presenting a robust counter-argument grounded in Israel’s consistent economic performance and the competitive nature of its bond offerings. The controversy fuels speculation that the Mamdani administration’s broader political stance against Israel may be influencing financial decisions, potentially causing New York City to overlook a historically reliable investment opportunity with attractive returns.
BOND YIELDS ARE HOVERING NEAR MULTI-YEAR HIGHS: WHAT IT MEANS FOR YOUR WALLET
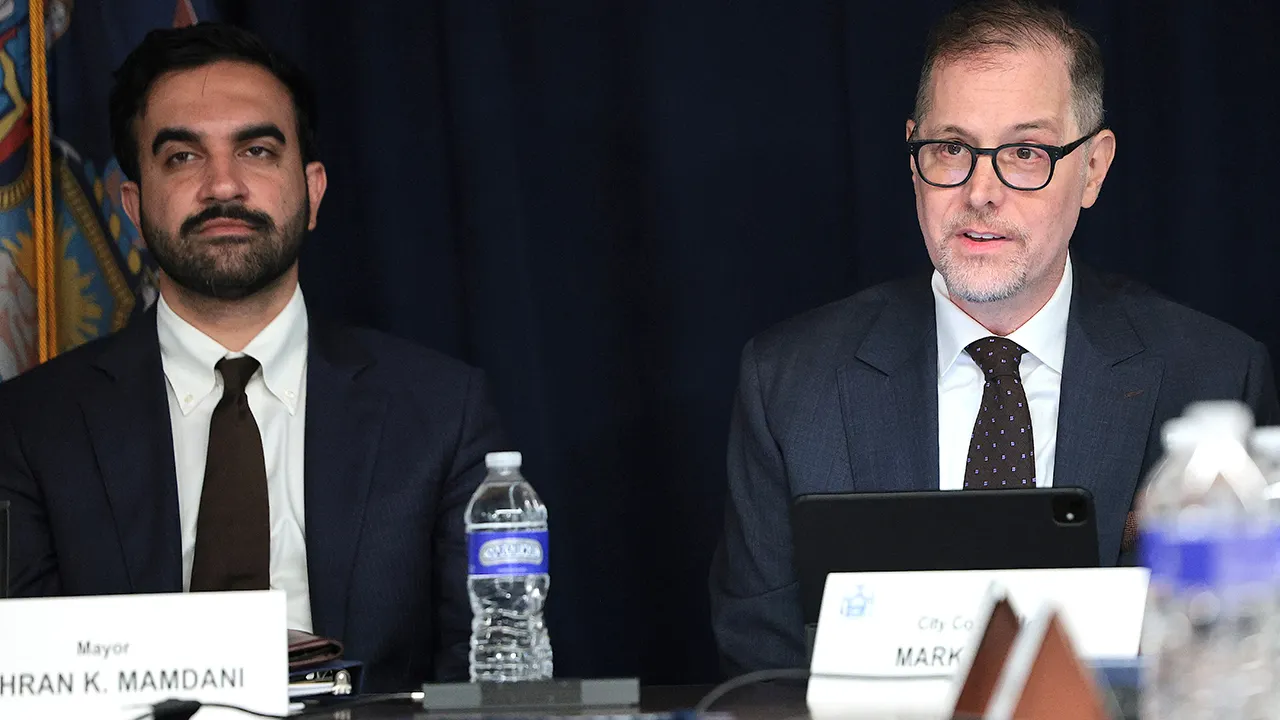
New York City Mayor Zohran Mamdani, left, listens as New York City Comptroller Mark Levine speaks during the annual New York State Financial Control Board meeting on Aug. 12, 2026 in New York City.(Michael M. Santiago/Getty Images / Getty Images)
In a market environment where investors are keenly seeking yield and stability, Naveh underscored Israel’s strong financial fundamentals. He highlighted that Israel Bonds offer compelling interest rates, with three-year Jubilee Bonds yielding 5.52% annually, five-year bonds at 6.02%, and 10-year bonds at 6.44%. These rates are particularly attractive in the current fixed-income market, offering a competitive edge against many alternative sovereign or municipal debt instruments, especially given Israel’s long-standing record of repayment.
“We learned of the comptroller’s decision when it was reported,” Naveh told FOX Business. “The city’s former comptroller had already broken with a 50-year tradition of investing in Israel Bonds, a tradition his predecessors kept even during times when Israel’s economy was vulnerable. We had hoped his successor would reverse that decision because, until recently, he had pledged many times” to restore New York City investment in Israel Bonds.
New York City’s direct investments in Israel Bonds commenced in 1974. The previous Comptroller, Brad Lander, had ceased renewing purchases as holdings matured in 2023. This current decision specifically pertains to New York City’s discretionary funds, not New York State, which continues its investments. Questions remain regarding whether pension assets or general treasury funds are affected, and if relevant pension trustees or union representatives were consulted prior to the decision. FOX Business’s inquiries to Levine’s office on these points, including requests for the financial analysis supporting his reversal, went unanswered by publication time.
“Investing in Israel Bonds is, first and foremost, a decision made in investors’ own financial interest,” Naveh said.(Kobi Wolf/Bloomberg via Getty Images / Getty Images)
Comptroller Levine cited “financial considerations” and “technical obstacles,” including a “New York City rule change on the short-term investment desk,” as reasons for departing from his campaign pledge. He told The New York Times, “I always said this would be based on financial considerations only, not politics,” though he subsequently noted purchases remained under evaluation. This explanation has only intensified scrutiny, prompting inquiries into what specific financial or regulatory shifts occurred between his consistent pledges and the ultimate decision, particularly in light of reports that the city may hold other bonds offering lower yields than Israel Bonds.
US ECONOMY ADDED 29,000 JOBS IN SEPTEMBER, A SLOWER PACE THAN EXPECTED
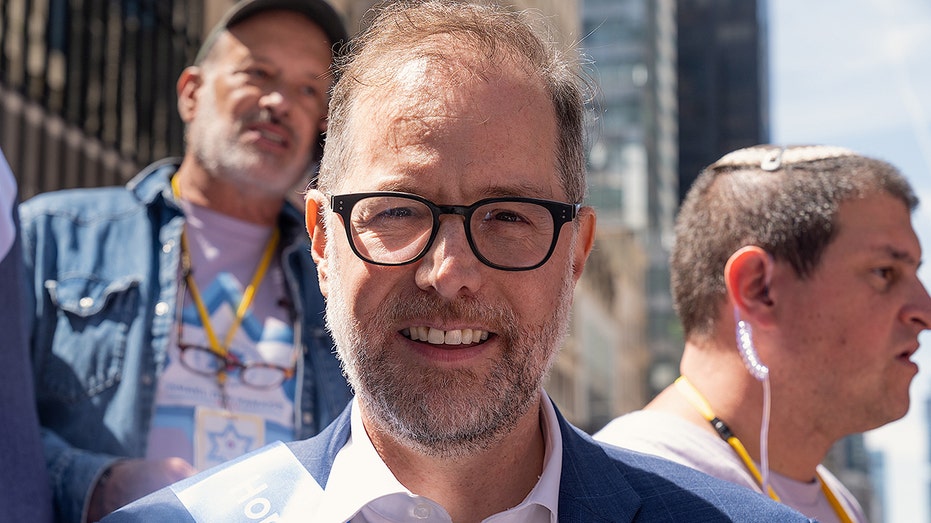
City Comptroller Mark Levine participates in the annual Israeli Day Parade on Fifth Avenue.(Lev Radin/Pacific Press/LightRocket via Getty Images / Getty Images)
Naveh emphatically reiterated the investment merits, stating, “Investing in Israel Bonds is, first and foremost, a decision made in investors’ own financial interest.” He emphasized the reliability factor, which is paramount for public pension funds and other long-term investors. “In 75 years, through wars, economic crises, and periods when its economy was far weaker than it is today, the State of Israel has never missed a single payment of principal or interest on its bonds. For retirees who count on their pensions, that kind of reliability matters,” he asserted.
Contrary to any suggestion of deteriorating financial conditions, Naveh presented a robust picture of Israel’s economy. “If anything, Israel’s financial picture has gotten stronger,” he argued. He cited projections from the Israeli Ministry of Finance and the Bank of Israel forecasting four percent growth in 2026, with the OECD projecting 5.6 percent growth for 2027. Key macroeconomic indicators remain strong: unemployment stands at approximately 3 percent, inflation around 1.6 percent, and Israel’s debt-to-GDP ratio is about 68 percent, significantly below the advanced-economy average of around 108 percent. These figures paint a picture of a resilient economy, reinforcing the investment-grade status of Israel’s sovereign debt.
The sun sets on the Statue of Liberty and the Empire State Building in New York City on July 28, 2025, as seen from Bayonne, New Jersey.(Gary Hershorn/Getty Images / Getty Images)
Furthermore, Israel maintains investment-grade ratings from all three major credit rating agencies: S&P and Fitch assign a solid A rating, while Moody’s holds a Baa1 rating. Notably, both S&P and Moody’s have recently raised Israel’s outlook from negative to stable, signaling enhanced confidence in the nation’s ability to manage its finances, even amidst regional tensions. Naveh highlighted a critical market indicator: “The cost of insuring Israel’s debt against default has fallen to around 59 basis points, near its prewar level,” suggesting that the market broadly perceives the risk profile of Israeli sovereign debt favorably, despite recent geopolitical events. While Israel Bonds products themselves are not rated, these sovereign assessments provide critical context for investor confidence.
Mark Goldfeder, CEO of the National Jewish Advocacy Center, echoed Naveh’s sentiments, asserting that Levine’s financial justifications are incorrect based on the available data. He emphasized that financial suitability should be the sole determinant for such investment decisions. Since October 7, 2023, more than 44 American local, state, and municipal governments, led by both Democrats and Republicans, have collectively invested nearly $4 billion in Israel Bonds, including the State of New York itself. This broad continued investment by other sophisticated public treasuries further underscores the perceived financial viability and appeal of Israel Bonds.
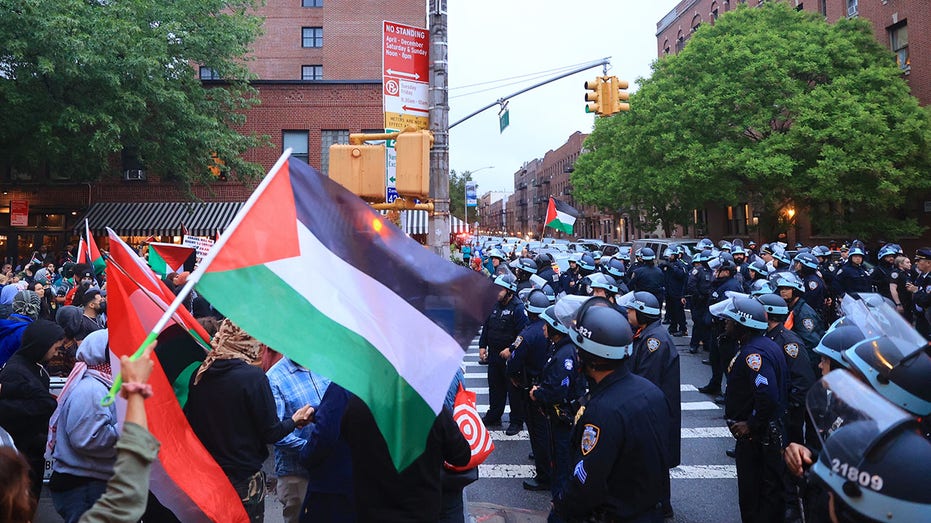
Anti-Israel protesters hold a rally in the Queens borough of New York City on May 15 to commemorate the 76th anniversary of Nakba Day.(Selcuk Acar/Anadolu via Getty Images / Getty Images)
ISRAEL’S ECONOMY FIGHTS TO RECOVER AS ISRAEL-HAMAS WAR RAGES ON
This decision by New York City’s Comptroller also brings into sharp focus the contentious issue of political influence on public investment decisions, especially as economic relationships with Israel face increasing scrutiny amid rising antisemitism. Naveh cautioned against giving credibility to “misleading narratives about Israel,” stressing the importance of “constructive dialogue based on economic facts.” He concluded, “The Comptroller had it right when he called Israel Bonds a long-term, safe and secure investment… If Israel Bonds are a sound investment for New York State, why not for New York City? Let the numbers guide this decision.”
Israeli and U.S. flags are seen in Kraków, Poland, on Sunday, August 28, 2022.(Artur Widak/NurPhoto via Getty Images / Getty Images)
CLICK HERE TO GET FOX BUSINESS ON THE GO
Market Impact:
New York City’s decision to forgo Israel Bond investments, particularly given the competitive yields and Israel’s robust financial profile, could send mixed signals to the municipal bond market and broader investment community. While the direct financial impact on NYC’s overall portfolio might be marginal, the controversy highlights a growing tension between purely financial considerations and the increasing pressure of geopolitical and social sentiment in public fund management. For Israel Bonds, while the majority of U.S. state and local governments continue to invest, a high-profile abstention from a major financial hub like New York City could create optics challenges, potentially raising questions among less informed investors, even if the underlying financial fundamentals remain strong. More broadly, it underscores the evolving landscape of fiduciary duty, where public officials are increasingly navigating demands to align investment strategies with political or social causes, even when such alignments may conflict with optimal financial returns or established investment criteria. This incident may prompt other municipal treasurers to more explicitly articulate their investment policies to insulate financial decisions from external political pressures, further emphasizing the need for transparency in public asset allocation.