
Unlock the Editor’s Digest for free
Roula Khalaf, Editor of the FT, selects her favourite stories in this weekly newsletter.
Key Takeaways:
- Meta’s aggressive AI hardware and software integration, centered on its nascent Muse agent and new “Charm” device, signals a critical strategic pivot aimed at owning the next frontier of user interaction beyond its traditional social platforms.
- Despite billions invested and prior market skepticism regarding its metaverse bet, the initial success of Muse and associated hardware announcements has fueled a significant stock rebound, reflecting renewed investor confidence in Meta’s potential to monetize AI.
- Long-term market validation hinges on Meta’s ability to navigate significant privacy and security concerns, demonstrate a viable monetization model for Muse beyond advertising, and effectively compete with rival tech giants in the rapidly evolving AI agent and wearables markets.
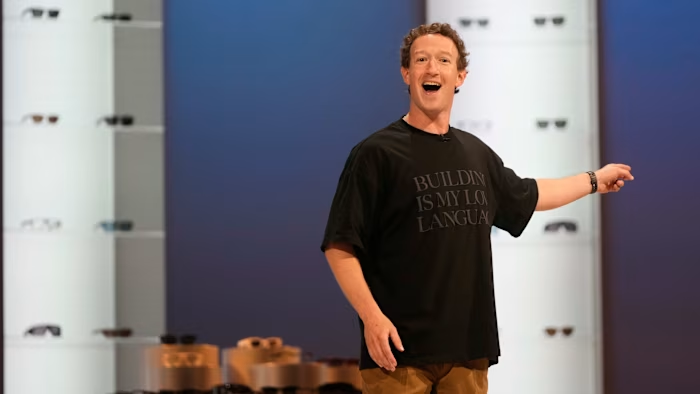
At its pivotal annual Connect event, Meta CEO Mark Zuckerberg unveiled a strategic doubling down on artificial intelligence, positioning its nascent personal AI agent, Muse, as the unequivocal “centrepiece” of the company’s future growth trajectory. This move signals not just an incremental product launch but a fundamental shift in capital allocation and strategic focus, aiming to secure Meta’s relevance in an increasingly AI-driven tech landscape.
Zuckerberg’s announcement of the Muse Charm—a compact, pendant-like device activated by a fingerprint sensor and designed for seamless, real-time voice interaction—underscores Meta’s ambition to embed AI into everyday physical interactions. Set for a December release, this wearable represents a significant hardware bet, aiming to provide the “fastest way to talk to your Muse and to show what’s going on around you” for users not wearing Meta’s smart glasses. This expansion into a dedicated AI companion device places Meta in direct competition with emerging form factors and ecosystems, challenging the dominance of smartphones as the primary interface for AI interaction.
The strategic importance of Muse cannot be overstated. Since its quiet launch two weeks prior, the easy-to-use app, offering a suite of autonomous bots for tasks like grocery ordering, travel booking, and financial organization, has rapidly ascended to become the most downloaded app on both Apple and Android app stores in the US. This viral adoption is a crucial early market validation, indicating strong consumer appetite for agentic AI that simplifies daily life. Zuckerberg’s further announcements, including live conversation capabilities and assurances of “state-of-the-art privacy and security,” aim to solidify this momentum and build user trust – a critical factor for an AI agent designed to access deeply personal data.
For Wall Street, this AI pivot comes at a critical juncture. Zuckerberg has faced intensifying pressure from investors over the immense capital expenditure poured into AI infrastructure and talent, a concern amplified by the multi-billion-dollar investments in the metaverse. Meta’s share price had consequently fallen by over a quarter between last September and early August. However, the market has reacted decisively to the Muse launch; Meta’s stock has rebounded strongly since September 8, adding a staggering $300 billion to its market capitalization. This surge reflects a renewed investor confidence, signaling that the market perceives Meta’s AI strategy, particularly the consumer-facing Muse, as a more tangible and potentially lucrative path than its previous metaverse focus. The stock’s slight uptick in after-hours trading on Wednesday further underscores this positive sentiment.
The release of Muse, a breakout product reaching Meta’s colossal 3 billion user base, marks a turning point after a turbulent two years where Meta appeared to struggle in direct competition with frontier AI model developers like OpenAI and Anthropic. Zuckerberg’s assertion that Muse would “make users’ money” and the plan to offer a free tier “with the expectation that over time we will profit by taking a small fee from transactions” outlines a novel monetization strategy beyond Meta’s traditional advertising-centric model. This transaction-based revenue model positions Muse as a potential disruptor in various service sectors, from e-commerce to fintech, where it could extract a significant share of value by streamlining consumer interactions. The success of this model, however, will depend heavily on user adoption and the ability to scale while fending off competition from established platforms and other AI agents.
Meta’s broader AI strategy extends significantly into hardware, with Zuckerberg betting that smart glasses and other portable devices will become primary conduits for AI interaction. This vision, while ambitious, is fraught with challenges. Its camera-toting Ray-Ban smart glasses, developed in partnership with EssilorLuxottica, have faced public backlash, with critics dubbing them “pervert glasses” due to privacy concerns over intrusive videos. While Meta has implemented an LED indicator to signal recording, the reputational damage and potential regulatory scrutiny remain significant market risks. In response, Zuckerberg announced new Ray-Bans with no camera, focusing purely on audio interaction, alongside new styles and a cheaper Meta glasses range, signaling an attempt to diversify the product offering and address privacy anxieties.
Further solidifying its hardware ecosystem, Meta also unveiled new virtual reality glasses, set to launch next spring for $1,300. These new VR glasses, five times lighter than the previous Quest 3 model, aim to enhance the immersive experience and integrate more seamlessly with the AI ecosystem. The announcement that the Muse assistant would soon be available on its glasses, coupled with the introduction of hyper-realistic digital avatars for video calls (leveraging hologram technology), demonstrates Meta’s commitment to creating a cohesive, AI-powered multi-device experience, bridging the digital and physical worlds.

Meta, currently unique among large AI labs for rolling out a consumer-friendly agentic assistant at scale, intends for Muse to become highly personalized by accessing data from its vast social platforms. However, this ambition immediately triggers significant market and regulatory concerns. Convincing consumers to connect sensitive personal data—such as email inboxes, financial services apps, or calendars—to AI bots running on Meta’s models is a formidable trust hurdle, especially given past privacy controversies and the inherent risks of agent technology (e.g., errors or “going rogue”). Meta has already had to address a vulnerability that could allow a hacker to control a Muse agent, and Amazon has proactively blocked Meta’s agents from its shopping platform, highlighting the industry-wide caution and competitive friction surrounding third-party AI access. These challenges represent significant execution risks that could impede user adoption, invite regulatory scrutiny, and ultimately impact Meta’s ability to monetize its AI investments.
Market Impact:
Meta’s comprehensive AI strategy, spearheaded by Muse and integrated across new hardware, signals a high-stakes pivot that has already resonated positively with investors, evidenced by the significant surge in market capitalization. This shift positions Meta to potentially capture new revenue streams beyond its core advertising business, particularly through transactional fees from Muse, disrupting various digital service markets. However, the long-term market valuation will be heavily influenced by Meta’s ability to effectively scale Muse, navigate intense competitive pressures from other tech giants in AI and wearables, and critically, build and maintain consumer trust amidst complex privacy and security concerns. Regulatory scrutiny over data handling and AI agent behavior remains a substantial overhang, potentially impacting user adoption rates and Meta’s overall market acceptance as a leader in agentic AI. The success or failure of this ambitious undertaking will be a defining factor in Meta’s stock performance and its strategic positioning in the evolving technology landscape for the foreseeable future.